Skip to content
Platform

Claims Automation Software — From FNOL to Settlement on One Record

Regure automates the work between the first notice of loss and the settlement decision: multi-channel intake, AI document extraction with confidence scores, document chasing, rules-based triage, authority-limited approvals and settlement. Run claims on Regure, replacing your legacy claims system one line at a time.

Claims Pipeline
SLA on track
Intake47
→
Review32
→
Adjust18
→
Settle12
CLM-2847 — Water damage
CLM-2846 — Collision

What insurance claims automation is — and what it is not

A typical claim passes through several people and systems before it is settled: notice of loss, policy lookup, document requests, approval, sign-off, settlement letter, signature. The problem is rarely that one step is slow. It is that the gaps between steps compound. A document arrives by email but nobody files it until the next day; an approval sits unseen in a supervisor's inbox.

Insurance claims automation removes those gaps. Claims automation software captures the notice, reads the documents, chases what is missing, applies your triage rules, routes reserves and payments to someone with authority to approve them, and generates the settlement paperwork. It does not replace adjuster judgement on coverage, liability or quantum. It means your adjusters spend their day on decisions, not on retyping and chasing.

For background, the complete guide to FNOL walks the first stage end to end, and our automated claims processing guide sets out where automation fits across the lifecycle.

FNOL to AssignmentNotices from every channel become structured claims and reach the right queue without manual triage
AI Document ExtractionPolice reports, estimates and invoices classified on arrival, each value with a confidence score
SLA MonitoringAutomated escalation when claims approach the deadlines you configure
Audit Trail by DefaultEvery extraction, chase, approval and payment recorded against the claim
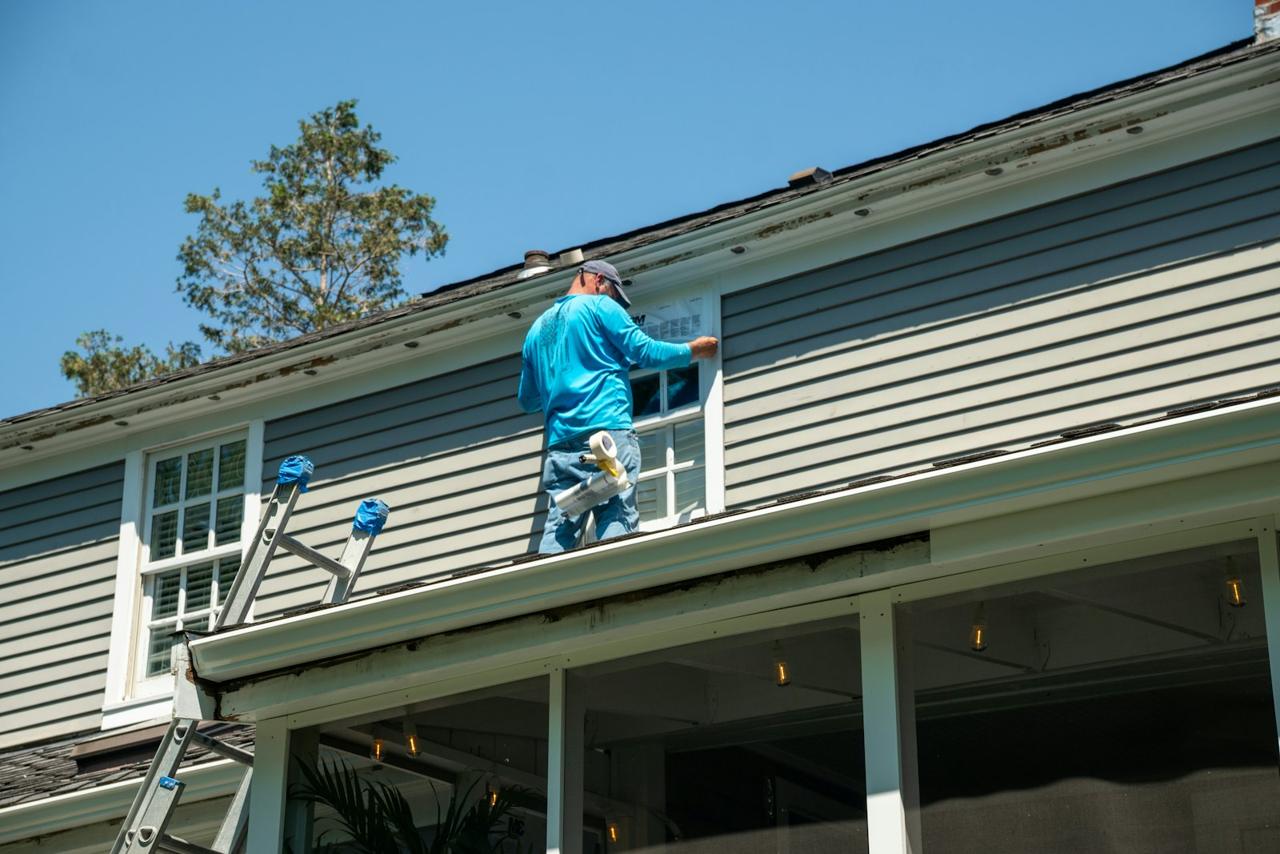
Adjuster inspecting storm damage on the exterior of a house
From site visit to settlement

The adjuster’s findings land on a complete file

Photos, estimates and inspection notes from the field attach to a claim that already holds the notice, the policy match and every document received so far. Nobody rebuilds the file before a decision can be made.

AI claims processing: document extraction with confidence scores

Most of the time lost on a new claim goes on reading attachments and typing what they say into the claims system. AI claims processing takes that work over, but only where it can show how sure it is.

Classify every attachment

When a document arrives, Regure identifies what it is: an ACORD loss notice, police report, repair estimate, invoice, medical report or photo. Classification decides where it is filed and which fields to look for. See document processing for document types and extraction options.

Extract fields with a confidence score

Policy number, date and cause of loss, location, claimant details and estimate totals are extracted and mapped to the claim record. Each value carries a confidence score, so a clearly printed policy number is treated differently from a smudged handwritten figure.

Send low-confidence values to a person

Values below the threshold you set are queued for a person to confirm before they reach the claim. The reviewer sees the source next to the value, corrects it if needed, and the correction is logged. Nothing uncertain is silently filed.

We do not quote a single accuracy percentage. Accuracy depends on your document mix, scan quality and how forms are filled in, so a number from someone else's documents tells you little about yours. In a demo, send your own redacted claim documents, set a threshold, and see what lands automatically and what goes to review.

FNOL automation: multi-channel intake into one claims queue

First notice of loss arrives through every channel: email, web portal, broker submission, API, and uploads from the field. Regure ingests from all of them, matches the notice to the policy, and creates a structured claim before a handler has to touch it.

FNOL is where claims teams lose the most time to rekeying. The police report goes to a general inbox, the photos to an adjuster's email, the estimate to a broker who forwards it on. None of it is linked to the claim until someone finds it.

Regure watches all intake channels at once and decides whether each arrival is a new notice or belongs to an open claim. For a new notice it creates the claim, classifies the loss type and applies your priority rules. For an existing claim, the document is filed to the right claim, so documents find the claim rather than the other way round.

For a US view, see FNOL automation for US MGAs. If most notices arrive by email, the email-to-claim use case shows one loss email becoming a claim file.

  • Email: notices sent to claims inboxes or forwarded by brokers
  • Web portal: policyholder and broker submissions with attachments
  • Call centre: phone notices logged into the same structured form
  • API: broker systems and partners submit FNOL via REST API
  • Scanned and faxed documents: classified and routed like any other file
FNOL Intake — Live Feed
10:23:41 — New FNOL via email
Auto collision, policy #AC-9102, est. $14,200
Classified: Auto → Assigned: J. Martinez (Sr. Adjuster)
10:24:03 — Document attached to CLM-2847
Police report (PDF, 3 pages) — classified: Supporting Evidence
Auto-linked to existing claim via policy number match
10:25:17 — New FNOL via broker API
Property water damage, 14 Oak Lane, est. $42,000
Classified: Property → Assigned: S. Thompson (Property Team)
10:26:44 — Missing document alert
CLM-2849: Medical authorization required — auto-request sent to claimant
Deadline: 72 hours per policy terms
Illustrative feed. Claim numbers, names and amounts are sample data showing how intake events appear to a claims team.

Automated document chasing that does not depend on who remembers

In most claims teams, chasing missing documents lives in personal follow-up lists. Claims stall because a reminder was never sent, not because anyone decided to wait.

Required-document lists per claim type

Each claim type has its own list of what a complete file needs: photos and an estimate for motor, a police report for theft, medical evidence for injury. Regure compares what has arrived against that list and identifies gaps before the adjuster opens the file.

Requests, reminders and a record of both

Missing items are requested from the claimant, broker or third party, with reminders on your schedule and escalation when a deadline passes. Every request and response is recorded, so you can see what was asked for, when, and what came back.

See Regure build a claim file from one of your FNOL emails

Send a redacted loss notice and its attachments. We will show you the claim Regure creates, the values it is confident about, and what it sends for review.

Claims triage and assignment rules you configure, not code

A small motor claim does not need a senior adjuster; a large commercial property loss should not go to a trainee. Regure routes every claim on rules your team controls, so similar claims follow the same path and you can show afterwards why.

Rule-based routing

Rules per line of business evaluate loss type, estimated value, location and coverage at intake. Motor claims under a threshold go to a Tier 1 team, large property losses to senior specialists, and claims in particular US states to adjusters licensed there.

Workload and expertise

Assignment can weigh open caseload, SLA position and adjuster skills, so a construction defect claim reaches someone with construction experience. For TPAs, balancing respects client boundaries.

Catastrophe surge

A pre-configured CAT mode redistributes claims across available adjusters, opens pools for independent adjusters and applies CAT authority limits approved in advance, so nobody rewrites rules mid-event.

Fraud indicators at intake

Incoming notices are checked against open and historical claims for likely duplicates and against the red-flag rules you define. Flagged claims route to your SIU or a senior adjuster with the reasons attached, not decided automatically.

Authority-limited reserves and payments

Settlement and reserving authority are the backbone of claims governance. When approvals run through email, they become the bottleneck. Regure enforces authority at the point of decision and keeps the evidence on the claim.

Most insurers and MGAs run tiered authority: handlers set reserves and approve payments up to one limit, seniors and managers to higher ones, with larger amounts referred to the carrier or capacity provider under the binding authority agreement. When the approval request is an email, it waits until someone notices it.

In Regure, limits are configured per role, line and claim type. A reserve or payment above an adjuster's limit cannot commit; it routes to an approver with the recommendation, documents and reserve history attached. Delegation passes requests to a named alternate when approvers are away, and every decision is logged in tamper-evident audit trails with who approved what, when and why.

  • Hard stop above authority until approved
  • Mandatory decision notes above thresholds you set
  • Escalation when an approval passes its SLA
  • Full history of every reserve movement and payment
Approval Queue — Claims Supervisor
CLM-2841 — Property $42K settlementPending 2h
CLM-2838 — Auto $18K repair estimatePending 45m
CLM-2835 — Liability $95K settlementApproved
CLM-2832 — Health $12K surgical authApproved
CLM-2829 — WC $67K reserve increaseDelegated

Automated claims settlement and payments

The last mile of the claim — settlement documents, signatures and payment — should not add another week of handoffs. Regure runs it from approval to closure.

Settlement document generation

Once a settlement is approved, Regure generates the settlement letter and release from pre-approved templates, configured per line and jurisdiction so the correct wording and disclosures appear without manual assembly.

E-signature collection

Releases go out through Regure's e-signature capability. Status is tracked on the claim and the signed, timestamped document is filed automatically.

Straight-through settlement for simple claims

For high-volume, low-complexity claims such as glass or minor property damage, you define the rules under which a claim settles without manual handling: coverage confirmed, documents complete, amount within automated authority, no fraud indicators. Anything that fails a rule goes to an adjuster. See straight-through processing.

Payment authorisation and closure

Signed settlements trigger the payment workflow, passing approved details to your finance or payments system through its API and recording status on the claim. The claim then closes and is archived under your retention policies.

Audit trail and regulator evidence from the claim file itself

Regulators increasingly ask insurers to show how claims were handled, not just what was paid. Claims automation is only useful to a compliance team if it leaves a better record than the manual process it replaced.

FCA Consumer Duty (UK)

Under the FCA's Consumer Duty, firms must evidence good customer outcomes, and claims handling is an area where friction and delay are scrutinised. Because every request, chase, decision and payment is timestamped, you can show how long each stage took and where claims waited. See UK compliance.

State DOI market conduct examinations (US)

State insurance departments sample claim files in market conduct examinations and test them against unfair claims settlement practices rules, including acknowledgement, investigation and payment timeframes. With a time-stamped history on each claim, files are produced from the system, not reconstructed from inboxes.

The same record supports carrier delegated authority audits and internal file reviews. The audit trail captures automated actions as well as human ones, so an accepted extraction and a reviewer's correction are both visible. The software produces the evidence; your compliance team owns the interpretation.

Claims automation by line of business

Claim types, required documents, routing rules, SLAs and authority limits are configured per line, so a single Regure instance can run several lines with separate operational logic. Start with one and add others without re-implementing.

Property

Water, fire, storm and theft claims with photo and estimate intake, loss adjuster appointments and CAT surge rules. See property claims automation.

Casualty

Liability and injury claims where solicitor correspondence, medical evidence and reserve movements need tight control. See casualty claims.

Auto

Motor FNOL, repair estimates, glass and total-loss workflows, with straight-through rules for simple repairs. See auto claims software.

Commercial

Commercial property, liability and package claims with broker-led notification and higher authority tiers. See commercial lines.

Specialty

Marine, cyber, professional and other specialty claims where expertise routing and delegated authority referral matter most.

Health

Medical and benefit claims with document classification, authorisation workflows and rules-based adjudication. See health claims.

Replacing Guidewire ClaimCenter, Duck Creek, Sapiens and Applied Epic claims

Regure replaces a legacy claims system in phases, by line or claim cohort. The work moves over in the order that pays back fastest, and there is no big-bang cutover.

Phase one: intake, documents and triage

The first phase usually takes the work that costs most to do by hand: intake, extraction, chasing and triage. Until a line's claim records migrate, completed claim data is passed to Guidewire ClaimCenter, Duck Creek Claims, Sapiens or Applied Epic through APIs. That bridge has an end date. See integrations and Regure vs Guidewire.

Then the claims system itself

Line by line or cohort by cohort, the claim record, reserves, payments, approvals and audit evidence move onto Regure and the legacy claims system is retired for that scope. MGAs, coverholders, TPAs and specialist programmes often run claims on Regure from day one. See how switching works and the modernization approach.

Implementation: start with a focused scope

A focused first scope, such as a single line of business without historical data migration, can be running in as little as 14 days. Broader scopes are planned with you and given a timeline in the proposal.

Pick the line where rekeying and chasing hurt most, configure its claim types, required documents, routing rules and authority limits, connect the intake channels, and test it against claims your handlers already know the answers to before switching that line over. Because these are configuration, not development, your claims team can adjust rules without raising change requests.

Then add lines, channels or integrations the same way. See our focused implementation guide.

Buyer's evaluation checklist for claims automation software

  • Does it show a confidence score for every extracted value, and route low-confidence values to a person?
  • Can it be tested on your own redacted claim documents before you sign?
  • Do email, portal, broker and API notices land in one queue, deduplicated against open claims?
  • Are required-document lists, routing rules and authority limits configuration your team controls?
  • Does a reserve or payment above authority hard-stop until it is approved?
  • Is every automated action, correction and approval recorded on the claim?
  • Can it replace your current claims system line by line, with APIs bridging the transition?
  • Where is your claims data hosted, and can you choose the region?

Where Regure is running today

Claims is part of each scope below. Named references are available under NDA during procurement.

Live in production

Swiss Lloyd's coverholder

Specialist medical insurance

Three insurance products configured on Regure, covering the operation end to end — from quoting through to Lloyd’s reporting — on Swiss data residency.

  • Quoting
  • Configurable rating
  • Policy administration
  • Claims
  • Commissions
  • Invoicing
  • Lloyd's bordereaux
  • Broker portal
  • Policyholder portal
  • Multilingual documents
  • Swiss data residency
Workflow evaluated against live practice

Reinsurance broking operation

Middle East / DIFC market

The reinsurance chain assessed end to end by practising reinsurance brokers, from submission intake through to closings and reporting.

  • Submission intake
  • Cedants
  • Placements
  • Markets
  • Shares
  • Premium
  • Closings
  • Debit / credit notes
  • Claims
  • Endorsements
  • Reporting
Operating today

Multi-region deployment

United States and Switzerland / Europe

Regure runs separate infrastructure per region, so data residency is a deployment choice rather than a custom build.

  • US deployment
  • Swiss / EU deployment
  • Regional data residency
  • Per-region infrastructure

Claims automation software FAQ

What is claims automation software?

Software that takes the administrative work out of the claim lifecycle: capturing FNOL from every channel, reading documents, chasing what is missing, triaging and assigning, routing reserves and payments for approval within authority, and producing settlement documents. Adjusters keep the judgement calls.

How does AI claims processing handle documents it is unsure about?

Every extracted value carries a confidence score. Values below your threshold go to a person to confirm before they reach the claim, and the correction is recorded. We do not quote a blanket accuracy figure; we test on your own redacted documents instead.

Can Regure replace our claims system?

Yes. Regure runs the full claims lifecycle and can replace a legacy claims system in phases, by line of business or claim cohort, with integration to Guidewire ClaimCenter, Duck Creek, Sapiens or Applied Epic during transition. Most move intake, documents and triage first, then the claim record itself line by line, retiring the legacy claims system as each line is accepted.

What is the difference between FNOL automation and claims automation?

FNOL automation covers the first stage: capturing the notice, matching it to the policy, creating and routing the claim. Claims automation also covers what follows, including document chasing, reserves, approvals, settlement, payment and closure.

Which lines of business can be automated?

Property, casualty, auto, commercial, specialty and health. Claim types, documents, routing and authority limits are configured per line, so you can start with one and add others.

Can settlement be fully automated?

For simple claims that meet every rule you configure and fall within automated authority, yes. Anything that fails a rule, exceeds authority or carries a fraud indicator routes to an adjuster with the evidence attached.

How does it help with FCA Consumer Duty and market conduct exams?

Every intake, extraction, correction, chase, approval and payment is recorded against the claim with who did it and when, so you can evidence claims handling for Consumer Duty or a state DOI market conduct examination from the file itself.

How long does implementation take?

A focused first scope, such as a single line of business without historical data migration, can be running in as little as 14 days. Broader scopes are planned with you and given a timeline in the proposal.

See claims automation on your own claims

Book a working session with your real claim types and a redacted FNOL. We will show you intake, extraction with confidence scores, triage, approvals and settlement configured for your lines of business.

Book a working session